
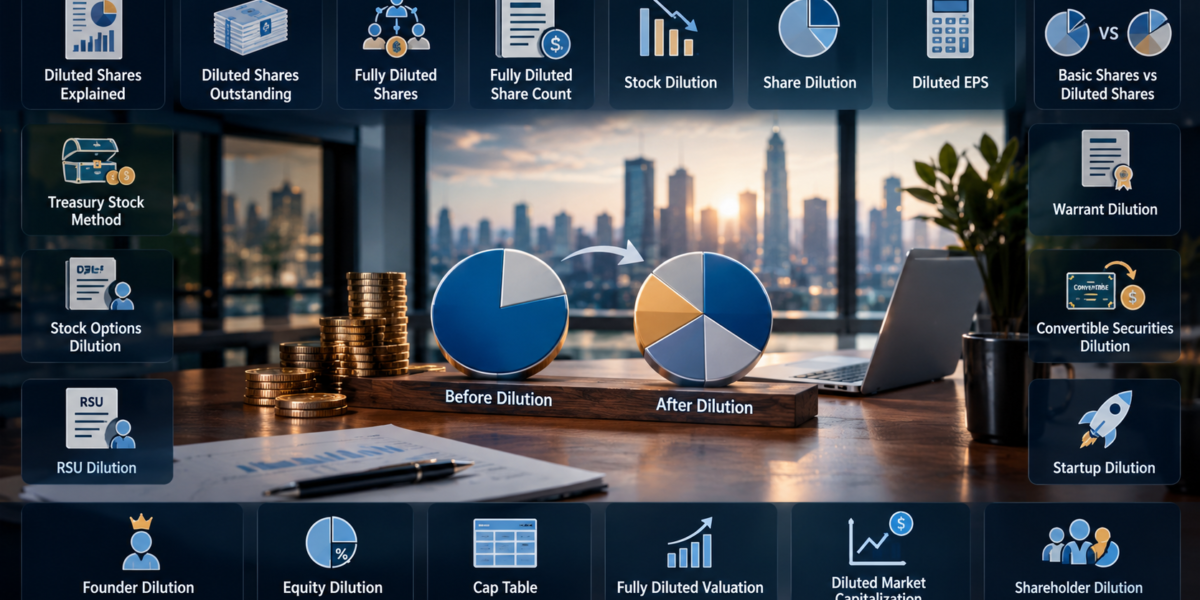
Ask a company how many shares it has and the answer depends on who is asking and why. The number on the cover of a filing is the shares currently outstanding. The number a buyer, investor, or employee needs often includes options, RSUs, warrants, and convertibles that could become shares later. Those extra shares are what diluted shares captures, and they change both your ownership percentage and your per-share math.
This guide covers the mechanics (basic vs diluted shares, the treasury stock method, diluted EPS), the startup side (cap tables, option pools, funding rounds, exit waterfalls), and the valuation side (market cap, enterprise value, M&A, IPOs). It is part of the wider ValuFlash library on finance, technology, and business. All companies and figures below are fictional and for illustration only.
Quick Answers
- Diluted shares are the basic shares outstanding plus the additional shares that could be created from options, RSUs, warrants, convertibles, and similar securities.
- Basic shares are the shares actually issued and outstanding today.
- Fully diluted shares is the broadest count, usually assuming all outstanding dilutive securities are exercised or converted. The exact method depends on the security and the purpose.
- Dilution reduces an existing holder’s percentage ownership. It does not automatically reduce the value of what they own.
What Are Diluted Shares?
Basic shares outstanding are the shares currently held by investors, founders, and employees. Diluted shares outstanding add the incremental shares that would exist if dilutive securities were exercised, vested, or converted. Fully diluted share count is the more expansive version, often used in capitalization tables and deal work.
Example. A company has 10,000,000 basic shares, 1,000,000 stock options, and 500,000 RSUs. An investor holding 1,000,000 shares owns 10% on a basic basis. If every option and RSU turned into a share, the total would be 11,500,000, and that investor would own 1,000,000 ÷ 11,500,000 = 8.70%.
Investors look beyond basic shares because the claim on the company’s value is shared with everyone who holds, or can obtain, shares. Ignoring them overstates your ownership and misstates per-share value.
Basic vs Diluted Shares
| Basic Shares Outstanding | Diluted Shares Outstanding | |
|---|---|---|
| What it represents | Shares issued and outstanding today | Basic shares plus incremental shares from dilutive securities |
| Typical use | Basic EPS, legal voting counts, current ownership | Diluted EPS, valuation, per-share value, deal analysis |
| Includes options/RSUs? | No (unless exercised or settled) | Yes, by an appropriate method |
| Includes convertibles? | No | Yes, if dilutive and applicable |
| Investor interpretation | Current ownership snapshot | Economic ownership if potential shares materialize |
Financial statements show multiple share counts because accounting rules define diluted EPS shares one way, weighted across a period, while a banker building a transaction model may use a point-in-time fully diluted count. Neither is wrong, but they answer different questions, so label which one you are using.
What “Fully Diluted” Means
Fully diluted shares outstanding (FDSO) counts the shares that would exist if potentially dilutive securities were converted or exercised. Common candidates:
| Security | How it can create shares |
|---|---|
| Stock options | Exercise at a strike price |
| Warrants | Exercise at a strike price |
| RSUs | Vest and settle in shares |
| Restricted stock | Often already issued; unvested portions may need separate treatment |
| Convertible notes | Convert at a price or discount |
| Convertible preferred | Convert at a stated ratio |
| Other equity-linked securities | Depends on terms |
Fully diluted counts are common in valuation and cap-table analysis because they show the broader claim on equity. The calculation is not universal. A venture cap table may count all granted and reserved options. A public-company valuation may count only in-the-money options via the treasury stock method. State your convention.
Why Stock Dilution Happens
- New share issuance: raising cash by selling stock.
- Startup fundraising: each priced round issues new preferred shares.
- Employee options and RSUs: equity compensation creates shares over time.
- Warrants: often issued to lenders or investors alongside financing.
- Convertible debt and preferred stock: conversion converts a fixed claim into shares.
- Stock-based acquisitions: paying for a target with shares expands the share count.
From the company’s perspective, issuing shares is a way to raise capital, attract talent, or buy a business without spending cash. From a shareholder’s perspective, each issuance shrinks their slice of the pie. Whether it is a good trade depends on what the company does with the capital or talent.
A Simple Dilution Example
A founder owns 1,000,000 of 2,000,000 shares: 50%.
The company issues 1,000,000 new shares to an investor. Total shares are now 3,000,000.
- Founder’s new ownership: 1,000,000 ÷ 3,000,000 = 33.3%
- Drop in ownership: 50% − 33.3% = 16.7 percentage points
- Relative dilution: (50 − 33.3) ÷ 50 = 33.3% of the founder’s original stake
Dilution is not inherently bad. Whether the founder is better off depends on what the new capital makes possible.
Dilution vs Company Value
Ownership percentage can fall while the value of a stake rises.
A founder owns 100% of a company valued at $5M. An investor puts in $2M, creating a $7M post-money valuation.
- Investor ownership = $2M ÷ $7M = 28.57%
- Founder ownership = 71.43%
- Founder stake before: 100% × $5M = $5M
- Founder stake right after: 71.43% × $7M = $5M
On day one the founder’s stake is worth the same, because the investor’s cash was added to the company. The benefit comes if the capital creates growth. Suppose the company, with the funding, reaches $15M. The founder’s stake is 71.43% × $15M = $10.71M. If it would only have reached $8M without the capital, the founder would hold $8M. In that scenario the founder owns less of a much bigger company. This is hypothetical, and funding can equally be wasted. The point is that dilution and wealth creation are not opposites.
Stock Options and the Treasury Stock Method
A stock option gives the holder the right to buy a share at a fixed exercise (strike) price. Key terms:
- Vested vs unvested: vested options can be exercised; unvested ones are still earned over time.
- In the money: the share price is above the strike, so exercising has value.
- Out of the money: the share price is below the strike, so exercising makes no sense.
Options dilute existing shareholders because exercising creates new shares, although the company receives the exercise price in cash.
The treasury stock method (TSM) estimates net new shares. It assumes holders exercise their in-the-money options, and the company uses the proceeds to repurchase shares at the current market price. Only the net increase counts.
Incremental Shares = Options − (Options × Exercise Price ÷ Current Share Price)
Equivalently: Incremental Shares = Options × (Market Price − Exercise Price) ÷ Market Price
Example. 1,000,000 options, $5 exercise price, $10 share price.
- Proceeds: 1,000,000 × $5 = $5,000,000
- Shares repurchased: $5,000,000 ÷ $10 = 500,000
- Incremental shares: 1,000,000 − 500,000 = 500,000
- Check: 1,000,000 × (10 − 5) ÷ 10 = 500,000 ✓
If the share price were $4, the options would be out of the money. Under TSM they add zero shares, and in diluted EPS they are treated as anti-dilutive and excluded.
RSUs
A restricted stock unit is a promise to deliver shares (or cash) once vesting conditions are met, typically time-based, sometimes performance-based. Unlike options, RSUs have no strike price, so they have value even if the share price falls. That makes them more dilutive per unit than options, which only create net shares when in the money.
Public companies commonly use RSUs for employees. Late-stage private companies use them too, often with a liquidity-event trigger. RSUs affect diluted share count as they vest and, for EPS, under accounting rules that treat unrecognized compensation as assumed proceeds. In simple valuation work, analysts often add outstanding RSUs in full.
Warrants
A warrant is a long-dated right to buy shares at a set price, usually issued to lenders or investors, often attached to a financing. It looks like an option, but it is typically issued to outside parties rather than employees, may have a different term, and is a distinct instrument on the cap table.
Example. 2,000,000 warrants with a $4 exercise price, share price $12. TSM: 2,000,000 × (12 − 4) ÷ 12 = 1,333,333 incremental shares.
Convertible Securities
- Convertible notes are debt that can convert to equity, often at a discount or valuation cap.
- Convertible preferred stock converts into common shares at a stated ratio.
- Convertible bonds are public-market debt convertible into common stock.
Conversion ratio example. 1,000,000 preferred shares converting 1:1.5 yield 1,500,000 common shares. A $5M note converting at $10 per share yields 500,000 shares.
Convertibles need care. Count the conversion shares or treat the instrument as debt, never both. Accrued interest, caps, discounts, and ratios can all alter the number of shares.
| Options | RSUs | Warrants | Convertibles | |
|---|---|---|---|---|
| Holder | Employees | Employees | Investors/lenders | Lenders/investors |
| Strike price | Yes | No | Yes | Conversion price/ratio |
| Value if stock falls | May be zero | Still positive | May be zero | Depends |
| Dilution method | TSM | Settled shares/TSM variants | TSM | If-converted |
Preferred Stock and Dilution
Preferred shares are not simply “more common shares.” They carry distinct economic terms:
- Liquidation preference: preferred holders receive their money back (often 1x) before common shareholders in a sale or liquidation.
- Participation: a participating preferred collects its preference and shares in the remaining proceeds. Non-participating preferred chooses one or the other.
- Conversion: preferred can usually convert to common, which it does when conversion gives a better payout.
On a cap table, preferred is counted on an as-converted basis for ownership percentages, but its payout rights can differ materially from its percentage. More on that in the exit section.
A Startup Cap Table
A capitalization table lists who owns what. Here is a fictional startup before and after a Series A.
Before funding
| Holder | Shares | Ownership |
|---|---|---|
| Founder A | 4,000,000 | 44.44% |
| Founder B | 3,000,000 | 33.33% |
| Early employees (common) | 500,000 | 5.56% |
| Option pool | 1,500,000 | 16.67% |
| Total | 9,000,000 | 100% |
Series A: $3M invested at a $9M pre-money valuation. Price per share = $9M ÷ 9,000,000 = $1.00. The investor receives 3,000,000 preferred shares.
After funding
| Holder | Shares | Ownership |
|---|---|---|
| Founder A | 4,000,000 | 33.33% |
| Founder B | 3,000,000 | 25.00% |
| Early employees (common) | 500,000 | 4.17% |
| Option pool | 1,500,000 | 12.50% |
| Series A investor (preferred) | 3,000,000 | 25.00% |
| Total | 12,000,000 | 100% |
Check: post-money = 12,000,000 × $1.00 = $12M, and the investor’s 25% equals $3M ÷ $12M ✓. Every holder was diluted by the same proportion.
Option Pool Dilution
Startups create an option pool to hire and retain employees. Investors usually want the pool large enough to cover planned hires before the next round, and they often insist the pool be created in the pre-money valuation, so existing holders bear the dilution, not the new investor.
Example. Founders hold 8,000,000 shares (100%). A new investor puts in $2M at an $8M pre-money valuation, a $10M post-money, so the investor owns 20%. The term sheet also requires a 10% post-closing pool.
- Investor: 20% of post-money shares
- Pool: 10%
- Founders: 70%, equal to 8,000,000 shares
- Total post-closing shares = 8,000,000 ÷ 0.70 = 11,428,571
- Investor shares: 2,285,714; pool shares: 1,142,857
- Price per share = $2M ÷ 2,285,714 = $0.875
- Founders’ effective pre-money = 8,000,000 × $0.875 = $7.0M, not $8M
Without the pool, founders would keep 80%. With it in the pre-money, they keep 70%. The headline valuation was $8M, but the pool made the real pre-money $7M. That is why founders negotiate both valuation and pool size.
Pre-Money vs Post-Money Dilution
Post-Money = Pre-Money + New Investment
Investor Ownership = New Investment ÷ Post-Money Valuation
| Pre-money | Investment | Post-money | Investor % | Existing holders % | |
|---|---|---|---|---|---|
| Round A | $8M | $2M | $10M | 20% | 80% |
| Round A with 10% post-closing pool in pre-money | $8M headline | $2M | $10M | 20% | 70% (+10% pool) |
Dilution Across Funding Rounds
A fictional founder through three rounds, each selling 20% of the company, with no option pool for simplicity:
| Round | Raise | Pre-money | Post-money | Founder % | Founder stake value |
|---|---|---|---|---|---|
| Start | n/a | n/a | n/a | 100% | n/a |
| Seed | $1M | $4M | $5M | 80% | $4M |
| Series A | $5M | $20M | $25M | 64% | $16M |
| Series B | $15M | $60M | $75M | 51.2% | $38.4M |
Check: after Series B, the founder holds 51.2% of $75M = $38.4M ✓. Seed investors hold 12.8%, Series A 16%, Series B 20%. Founders should track both ownership percentage and the value of ownership; a 51% stake in a $75M company is a different outcome than a 100% stake in a stagnant one. Real rounds also add pools, SAFEs, and secondary sales, so actual ownership falls further.
Building the business that earns those valuations is the point. Hiring, infrastructure, and scalability all shape what investors will pay, a theme in the real engineering process behind successful startups.
Employee Equity: What to Ask
For employees, a number of options means little without context. Checklist:
- How many shares am I granted, and what percentage of fully diluted shares is that?
- What is the strike price, and what is the latest valuation?
- What is the vesting schedule and cliff?
- How large is the option pool, and how much is unallocated?
- What preferences sit ahead of common stock?
- How much further dilution should I expect?
- What is the exercise window after leaving the company, and how would I pay the exercise cost and taxes?
- When could a liquidity event realistically happen?
Illustration. 40,000 options at a $2 strike, with 20,000,000 fully diluted shares, equals 0.2%. If the company were sold for $100M of equity value (ignoring preferences and further dilution), value per share = $5, and the spread is $3 × 40,000 = $120,000 before taxes. Private-company equity is a risky, illiquid outcome, not guaranteed wealth. Most scenarios involve further dilution and preferences, and some end at zero.
Diluted EPS
Basic EPS = Net income available to common ÷ Weighted-average basic shares
Diluted EPS = Adjusted net income ÷ Weighted-average diluted shares
Diluted EPS accounts for potential common shares. Options and warrants use the treasury stock method. Convertibles use the if-converted method: assume conversion, add back after-tax interest (or preferred dividends) to the numerator, and add the conversion shares to the denominator.
Example. Net income is $12M with 10,000,000 basic shares.
- Basic EPS = 12,000,000 ÷ 10,000,000 = $1.20
- Add options (500,000 net via TSM at an average $10 price) and RSUs (500,000, simplified): shares = 11,000,000, EPS = 12,000,000 ÷ 11,000,000 = $1.09
- Add a $5M convertible bond paying 4% interest, convertible into 400,000 shares, with a 25% tax rate. After-tax interest = 5,000,000 × 4% × (1 − 0.25) = $150,000. Net income = $12,150,000; shares = 11,400,000. Diluted EPS = $1.07 (rounded)
| Metric | Basic EPS | Diluted EPS |
|---|---|---|
| Shares used | Weighted-average shares outstanding | Basic plus dilutive potential shares |
| Potential dilution | Ignored | Included if dilutive |
| Options | Ignored | TSM, if in the money |
| Convertibles | Ignored | If-converted, if dilutive |
| Investor interpretation | Earnings per current share | Earnings per share on a more conservative basis |
Diluted EPS is lower than (or equal to) basic EPS because it spreads earnings across more shares. It cannot be higher, because anti-dilutive securities are excluded.
Anti-Dilutive Securities
A security is anti-dilutive if including it would increase EPS (or reduce a loss per share). Accounting rules require excluding those from diluted EPS. Examples: options with a strike above the average share price; a convertible whose after-tax interest per conversion share exceeds basic EPS (the bond above adds $150,000 ÷ 400,000 = $0.375 per share, below $1.09 EPS, so it is dilutive; if it were $1.50 per share, it would be excluded).
This is why accounting dilution is not identical to a fully diluted ownership analysis. An out-of-the-money option is excluded from diluted EPS, but a cap table still shows it, and a buyer may care about it if the deal price exceeds the strike. Never assume every potential share appears in every calculation.
Diluted Shares in Valuation
Equity Value = Share Price × Appropriate Share Count
The “appropriate” count depends on the question. For valuation, analysts generally use diluted shares because options and RSUs are claims on equity value.
Example. Share price $10; basic shares 10,000,000; net new shares from options and RSUs 1,000,000.
- Basic market cap = $100M
- Fully diluted equity value = 11,000,000 × $10 = $110M
Sources can report different market-cap numbers because they use different share counts, share classes, or dates. Always check definitions and as-of dates. The same applies in IPO valuation, acquisitions, and comparable-company analysis, where inconsistent counts distort multiples.
Diluted Shares and Enterprise Value
Enterprise Value = Equity Value + Net Debt
The flow: Share Price → Diluted Shares → Equity Value → Enterprise Value.
Continuing the example, with $35M of debt and $15M of cash, net debt = $20M.
- Using basic shares: EV = $100M + $20M = $120M
- Using diluted shares: EV = $110M + $20M = $130M
The $10M gap would flow straight into EV/EBITDA and every other EV multiple. Dilution is not debt, and the two should not be confused. They are separate adjustments, which is why the share count belongs at the start of the bridge.
Diluted Shares in M&A
In an acquisition, the buyer pays for everyone who has a claim on equity, so it must understand the true capitalization: options, RSUs, warrants, convertibles, and their acceleration terms.
Example. An acquirer offers $12 per share, in cash, for a company with 10,000,000 basic shares, 1,000,000 options at a $5 strike, and 500,000 RSUs that accelerate on a sale.
- Options via TSM at $12: 1,000,000 × (12 − 5) ÷ 12 = 583,333
- RSUs: 500,000
- Diluted shares: 11,083,333
- Equity purchase price: 11,083,333 × $12 = $133M (vs $120M on basic shares)
- With $20M of net debt, EV = $153M
Option holders actually receive the spread (12 − 5) × 1,000,000 = $7M, which matches 583,333 × $12. A buyer who used basic shares would miss $13M of cost.
Stock-for-Stock Deals
When the consideration is shares, existing shareholders on both sides are diluted. The exchange ratio sets how many acquirer shares each target share receives.
Example. The acquirer has 50,000,000 shares at $20. The target has 10,000,000 fully diluted shares. Exchange ratio: 0.5.
- New acquirer shares issued: 10,000,000 × 0.5 = 5,000,000
- Combined shares: 55,000,000
- Pro forma ownership: acquirer holders 90.91%, target holders 9.09%
- Implied offer per target share: 0.5 × $20 = $10, so a deal equity value of $100M
Dilution and IPOs
An IPO usually issues new primary shares (raising cash for the company) and sometimes includes secondary shares sold by existing holders (no new shares, no cash to the company). Employee options and RSUs often become tradable after lockups expire.
Example. A company has 40,000,000 fully diluted shares pre-IPO and issues 10,000,000 primary shares at $15. Post-IPO shares: 50,000,000. New investors own 20%; existing holders drop from 100% to 80%. Fully diluted market value at the IPO price = 50,000,000 × $15 = $750M. A headline share price tells you little until you know the fully diluted count, the lockup schedule, and the unvested equity still to come.
Dilution vs Stock Splits
A stock split changes the number of shares and price per share, but not proportional ownership or company value.
Example. A 2-for-1 split turns 1,000 shares at $50 ($50,000) into 2,000 shares at $25 ($50,000). Everyone’s percentage stays the same. Options and RSUs are adjusted accordingly. By contrast, issuing new shares to new holders reduces everyone else’s percentage. Don’t treat a split as dilution.
Stock-Based Compensation and Dilution
Equity compensation motivates employees and conserves cash, but it has two costs: an accounting expense (recognized over the vesting period) and share-count growth. Investors should look at both. Excluding SBC from adjusted EBITDA flatters earnings without removing the dilution, and the offsetting share buybacks consume real cash. For AI-native and software businesses where talent is a key cost, equity costs deserve attention in any analysis of operating economics, as explored in how to build an AI-first business system.
Dilution and Startup Valuation
Valuation, fundraising, cap tables, option pools, and exit outcomes are tied together. A founder with 51.2% of a $75M company (from the multi-round example) holds more value than a founder with 100% of a $5M company. Technical and product decisions help drive that valuation, which is why choices like choosing the right tech stack can influence cost structure, speed, and investor confidence. Still, outcomes vary widely, and more rounds mean more dilution.
Exit Value and Liquidation Preferences
Ownership percentage alone does not decide who gets what at an exit. Contractual terms matter: liquidation preference, participation, and conversion decide the waterfall.
Fictional cap table: founders 50%, employees (assumed fully vested and exercised, ignoring strike prices for simplicity) 10%, Series A investors 40%, who invested $20M with a 1x preference.
| Scenario | Series A | Founders | Employees |
|---|---|---|---|
| $100M exit, non-participating (A converts: 40% = $40M > $20M) | $40M | $50M | $10M |
| $100M exit, participating (A takes $20M + 40% of $80M) | $52M | $40M | $8M |
| $30M exit, non-participating (A takes $20M preference over 40% = $12M) | $20M | $8.33M | $1.67M |
Check: each row sums to the exit value. In the $30M case, the founders hold 50% but receive about 27.8% of proceeds. Further rounds, debt, transaction costs, and management carve-outs can change this again. Actual terms are in the legal documents.
Modeling Diluted Shares
In a financial model, the share count should be dynamic: linked to the cap table, option grants, vesting, convertibles, financing rounds, and the share price used (because TSM depends on price). Hardcoded share counts break when valuation changes. Model:
- Cap table by security and class
- Option pool and grants
- Conversion terms of notes and preferred
- Financing rounds and exit scenarios
- Per-share value and EPS
When the share price changes, TSM changes, the diluted count changes, and equity value changes. A circularity can result (price depends on value, which depends on shares), so many models iterate or use the offer price as an input.
Common Dilution Mistakes
| Mistake | Solution |
|---|---|
| Using basic shares when diluted are needed | Match the share count to the purpose |
| Ignoring options, RSUs, warrants, or convertibles | Build a full securities schedule |
| Misunderstanding option pools | Check whether the pool is pre- or post-money |
| Confusing dilution with loss of value | Compare stake value, not just percentage |
| Ignoring preferred rights | Model the waterfall |
| Assuming all potential shares are immediately dilutive | Apply TSM and test for anti-dilution |
| Confusing splits with dilution | Check whether new holders or new capital are involved |
| Using outdated cap tables | Confirm the as-of date with the latest filing or company data |
| Ignoring future fundraising | Model expected dilution in scenarios |
How to Calculate Fully Diluted Shares
- Start with basic shares.
- Identify options.
- Identify warrants.
- Identify RSUs.
- Identify convertible securities.
- Determine conversion terms.
- Apply the appropriate method (TSM, if-converted, or full count).
- Remove anti-dilutive securities where the purpose requires it.
- Total the diluted share count.
- Verify against the cap table and financial statements.
The right method depends on the purpose. An EPS calculation follows accounting rules. A valuation may use a current share price and TSM. A startup cap table may count all granted and reserved options. Real calculations can require security-specific terms and legal or accounting review.
Career Applications
Equity analysts, bankers, VC and PE professionals, FP&A teams, corporate finance, startup finance leads, CFOs, and entrepreneurs all work with share counts. Mistakes in this area show up directly in deal prices, valuation multiples, and founder outcomes. Useful skills: accounting, financial statement analysis, financial modeling, valuation, Excel, cap-table analysis, and corporate finance. For a broader view, see building skills that create long-term business value.
Practical Learning Projects
- Project 1: Build a basic startup cap table. Teaches ownership math and share classes.
- Project 2: Model founder dilution through Seed and Series A. Teaches pre/post-money and option pools.
- Project 3: Calculate diluted EPS. Teaches TSM and if-converted methods.
- Project 4: Build a treasury stock method example. Teaches how price drives share count.
- Project 5: Create an acquisition capitalization model. Teaches equity purchase price and pro forma ownership.
- Project 6: Model a startup exit waterfall. Teaches preferences, participation, and conversion.
30-Day Learning Roadmap
| Week | Focus | Exercise |
|---|---|---|
| 1 | Shares, ownership, market cap, cap tables | Build a three-holder cap table |
| 2 | Options, RSUs, warrants, convertibles | Compute fully diluted shares for a sample company |
| 3 | Diluted EPS, TSM, valuation | Calculate basic and diluted EPS; bridge to EV |
| 4 | Full dilution and exit model | Model two funding rounds and an exit waterfall |
Frequently Asked Questions
What are diluted shares in simple terms?
Diluted shares are the shares outstanding today plus the extra shares that could be created from options, RSUs, warrants, and convertibles.
What is the difference between basic and diluted shares?
Basic shares are those actually outstanding. Diluted shares add potential shares from dilutive securities, giving a more conservative picture of ownership and per-share value.
What does fully diluted mean?
Fully diluted generally means counting all potentially dilutive securities, usually assuming exercise or conversion. The exact method depends on the purpose.
Why do companies have diluted shares?
Companies issue options, RSUs, warrants, and convertibles to compensate employees, raise capital, and structure financings. Those instruments can later become shares.
How do stock options affect dilution?
Exercised options create new shares. Under the treasury stock method, only in-the-money options add net shares to diluted counts.
Do RSUs dilute shareholders?
Yes. When RSUs vest and settle in shares, the share count rises. Unvested RSUs are generally considered in diluted counts under the applicable rules.
What is the treasury stock method?
It estimates net new shares from options and warrants: Options × (Market Price − Exercise Price) ÷ Market Price.
What is diluted EPS?
Diluted EPS is net income per share, calculated using shares that include dilutive potential shares (and adjusted earnings for convertibles).
Is shareholder dilution always bad?
No. Ownership percentage falls, but the stake can be worth more if the capital or talent increases company value enough.
How does fundraising dilute founders?
New investors receive shares, so founders’ percentage falls. Option pool increases in the pre-money can add further founder dilution.
How do diluted shares affect market capitalization?
Using diluted shares raises market cap relative to basic shares, because more shares are multiplied by the same price.
What is a fully diluted cap table?
It lists ownership on an as-converted, fully counted basis, including options, pool, warrants, and convertibles.
What is the difference between dilution and a stock split?
A split changes the number of shares and price per share but not proportional ownership. Dilution reduces an existing holder’s percentage.

Leave a Reply